Chase Credit Card Eligibility: Why Low Credit Scores Get Rejected & What Are Your Options
Chase credit cards have strict official eligibility rules, rejecting applicants with low credit scores or 6-year CCJ, IVA and bankruptcy records. Discover valid credit alternatives if your application fails.
Chase credit cards are extremely popular among users for their attractive perks, including competitive cashback rewards and zero overseas transaction fees. However, unlike regular credit cards with flexible entry requirements, Chase enforces very strict official eligibility criteria that rule out a large number of applicants with imperfect credit profiles.
Most rejected applicants have no idea they fail the fixed background rules, even with a steady income and clean recent payment history. Understanding these hard limits will help you know your approval odds and find suitable backup credit solutions.
Non-Negotiable Official Chase Credit Card Rules
According to official policy, a Chase credit card application will be automatically declined if you fail any of the following mandatory checks. These rules apply to all applicants with no exceptions:
- Mandatory account requirement: Only existing Chase current account holders are eligible to apply; new non-account holders cannot submit applications
- 6-year clean credit record rule: Any bankruptcy, CCJ (County Court Judgement), or IVA (Individual Voluntary Agreement) recorded in the last 6 years will cause an immediate rejection
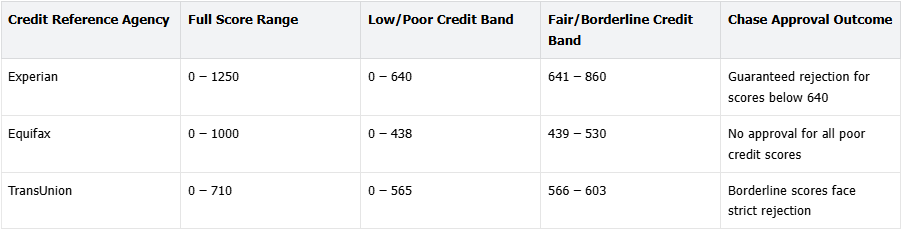
- Strict credit score screening: Low or borderline credit scores do not meet Chase’s creditworthiness standards, leading to automatic application failure
- Full affordability assessment: Applicants must pass strict income and outgoing checks to prove reliable repayment ability
Credit Score Tiers & Chase Card Approval Possibility
Credit scores are graded differently across the three major credit reference agencies. There is no universal scoring standard, and any score classified as low or poor will almost certainly be rejected by Chase. The table below clearly shows your approval chances based on official score brackets:
Why Most Users Searching for Chase Cards Get Rejected
Most users search for Chase credit cards because of its premium benefits, but they overlook the rigid background checks. Even if you have no recent missed payments, the following issues will disqualify your application:
A low credit score, past 6-year adverse credit records including CCJs, IVAs or bankruptcy, and not holding a Chase current account are the three top reasons for rejection. Mainstream banks follow similar strict rules, leaving low-credit users with few formal credit options.
Alternative Credit Options If Your Chase Application Fails
If you have been rejected for a Chase credit card due to low credit or past credit issues, you still have accessible, regulated credit solutions. Specialist authorised lenders focus on your current affordability rather than outdated credit mistakes.
These providers welcome applicants with low credit scores, previous defaults, missed payments and borderline credit profiles. Initial eligibility checks use soft credit searches that leave no marks on your credit file, protecting your future credit applications.
All partnered lenders are fully regulated, offering transparent terms and flexible repayment plans for users who cannot access mainstream credit products.
Practical Solutions After Chase Credit Card Rejection
If your Chase credit card application is declined, you do not need to keep submitting repeated credit applications, as multiple hard searches will further damage your credit rating. Here are actionable solutions for your situation:
1. Credit-builder credit cards
These cards are designed specifically for people rebuilding credit. They usually come with lower starting credit limits and higher representative APR. If you use them carefully, spend small amounts and clear the full balance each month, you can gradually improve your credit file over 6–12 months. After building better credit, you can recheck eligibility for mainstream credit products later.
2. Specialist unsecured credit for imperfect credit profiles
FCA-authorised specialist lenders focus more on your current affordability rather than old credit mistakes. They accept applications from users with low credit scores, past defaults or old CCJ/IVA records. Initial eligibility checks use soft searches that leave no footprint on your credit report, so checking eligibility will not harm your score.
3. Check your credit report and fix errors
Pull your free credit file from major reference agencies. Sometimes incorrect negative entries cause your application to fail. You can submit disputes to remove inaccurate information, which may lift your credit score.
4. Debt advice if you struggle with existing repayments
If you already have unmanageable debts, seek free independent debt advice before taking new credit. Independent advisors can help arrange affordable repayment plans.
Important tip: Avoid applying for many credit products quickly in a short window. Every full application creates a hard search and hurts your credit score further. Use soft eligibility checks first wherever possible.
FAQ
Q: Can I get a Chase credit card with a low credit score?
A: No. Chase’s strict credit rules automatically decline applications with low or borderline credit scores, regardless of current income status.
Q: Will past CCJ or IVA records block my Chase card application?
A: Yes. Any CCJ, IVA or bankruptcy record within the last 6 years leads to mandatory rejection by official policy.
Q: Do I qualify if I do not have a Chase current account?
A: No. Holding an active Chase current account is a compulsory prerequisite for all credit card applications.
Warning: Late repayment can cause you serious money problems. For help, go to moneyhelper.org.uk
Disclaimer: We are a credit broker, not a direct lender. We work with a panel of FCA-authorised lenders and may receive commission for successful referrals. No upfront fees apply. This content is for informational purposes only and is not affiliated with Chase.